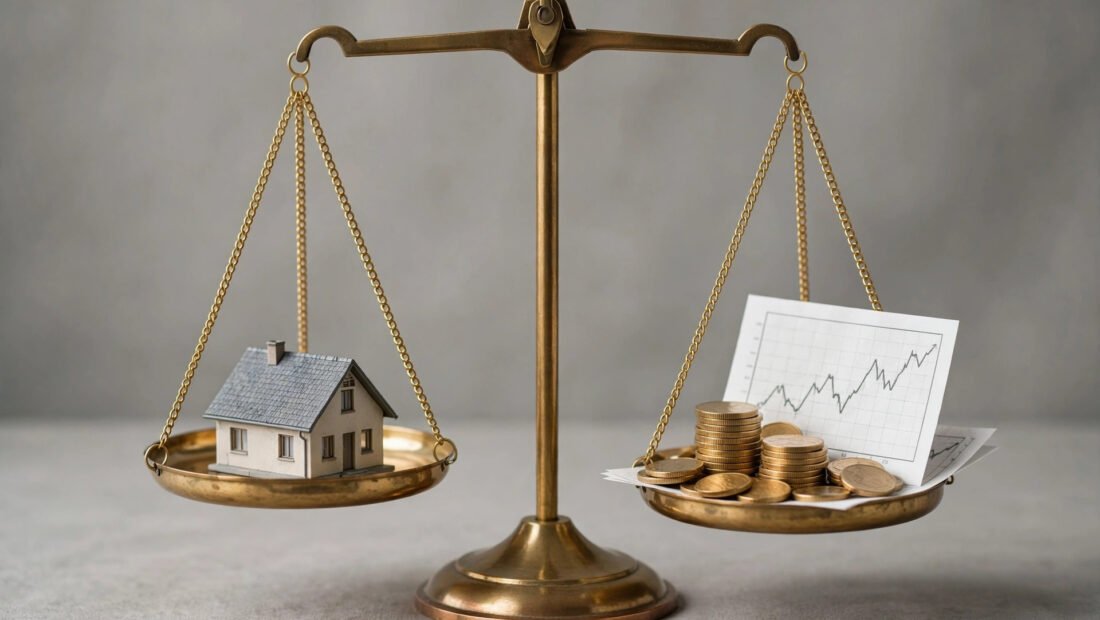
You have an extra $500 a month. (If you don’t yet, tools that help you stick to a monthly budget can help you find it.) Do you send it to the mortgage company or to your brokerage account? It is one of the most consequential personal finance questions a Texas homeowner faces, and the internet’s answer is usually whatever the answerer did themselves. The truth is less satisfying: it depends on your mortgage rate, your tax situation, your timeline, and your tolerance for risk. This guide gives you the actual decision framework — the math, the psychology, and the Texas-specific wrinkles — so you can answer it for your own household instead of someone else’s.
The Core Math: Guaranteed Return vs. Expected Return
Every extra dollar toward your mortgage earns a guaranteed, after-tax return equal to your mortgage rate. With a 7 percent mortgage, prepaying is equivalent to buying a risk-free bond yielding 7 percent — an extraordinary guaranteed return by historical standards. With a 3 percent mortgage from the low-rate era, prepaying earns 3 percent guaranteed, while long-run stock market returns have averaged roughly 10 percent nominal (about 7 percent after inflation). The spread between those numbers is the entire debate.
Put concretely: $500 extra monthly on a $300,000, 7 percent, 30-year mortgage saves roughly $150,000 in interest and cuts about 9 years off the loan. The same $500 invested monthly at a 7 percent average return grows to a similar neighborhood — but with volatility, sequence risk, and no guarantee. At 7 percent mortgage rates, prepayment is mathematically compelling. At 3 percent, investing usually wins on expected value. Between 4 and 6 percent, it is genuinely close, and secondary factors decide.
One nuance beginners miss: mortgage interest deductibility. If you itemize, the after-tax cost of your mortgage is lower than the headline rate. In practice, most Texas homeowners take the standard deduction (especially since the 2017 tax changes), which means the mortgage rate is the true hurdle rate for most households. The IRS guidance on interest deductions covers when deducting actually applies, and FINRA’s investor education resources explain how to weigh expected market returns against guaranteed ones.
The Case for Paying Off the Mortgage Early
- Risk-free return. No market investment offers 6 to 7 percent guaranteed. Prepayment at today’s rates is the best risk-adjusted deal available to most households.
- Cash flow freedom. Eliminating a $2,000 monthly payment transforms retirement math, career flexibility, and resilience to income shocks. The psychological value is real and measurable — surveys consistently show mortgage-free homeowners report far less financial anxiety.
- Texas property tax reality. Here is the wrinkle Texans must price in: paying off the mortgage does not end housing costs. With 1.6 to 2.2 percent property taxes plus insurance, a “paid-off” $400,000 Texas home still costs $800 to $1,100 monthly. Factor that in before romanticizing the payoff date.
- Forced discipline. Extra principal payments are automatic wealth-building for people who would otherwise spend the surplus.
- Interest savings are enormous at high rates. On a 7.5 percent loan, the total interest over 30 years can nearly equal the principal borrowed. Prepayment attacks the most expensive debt most households will ever carry.
The Case for Investing Instead
- Higher expected returns. Over long horizons, diversified equity investing has beaten mortgage rates in most historical periods — especially against sub-5 percent mortgages.
- Liquidity. Money in a brokerage account is accessible; home equity is not (without selling or borrowing). Households with thin emergency funds should build liquid reserves before prepaying aggressively.
- Inflation hedge. A fixed-rate mortgage is one of the best inflation hedges available: you repay with cheaper future dollars while the asset appreciates nominally.
- Tax-advantaged space is use-it-or-lose-it. Unused 401(k) and IRA contribution room disappears each year. Funding tax-advantaged accounts before prepaying a low-rate mortgage is usually optimal — the tax benefit alone often exceeds the rate spread.
- Employer match. Never prepay a mortgage before capturing a full 401(k) employer match. That is an instant 50 to 100 percent return no prepayment can touch.
Investors weighing where extra cash works hardest should also understand how their housing costs interact with their broader budget — how to create a family budget that actually works gives a framework for allocating surplus dollars across competing goals.
The Hybrid Approach Most Experts Actually Recommend
The binary framing is false; most households do best splitting the surplus. A practical hierarchy:
- Capture the full employer 401(k) match.
- Build a 3-to-6-month emergency fund in a high-yield savings account.
- Eliminate high-interest debt (credit cards, personal loans).
- Max tax-advantaged retirement contributions if your mortgage rate is below ~6 percent; split between retirement and prepayment if above.
- With remaining surplus, split between taxable investing and mortgage prepayment according to your risk tolerance.
This approach captures guaranteed wins first, preserves liquidity, and still attacks the mortgage. It also adapts: if rates fall and you refinance to 5 percent, shift more toward investing; if rates rise, shift toward prepayment.
Texas-Specific Considerations
Homestead protections. Texas has the nation’s strongest homestead protections — unlimited value shielded from most creditors. Every dollar of home equity sits behind that shield, which marginally favors prepayment for Texans with liability exposure (business owners, physicians).
No state income tax. This cuts both ways: there is no state tax benefit to mortgage interest, making the effective cost of the mortgage slightly higher than in high-tax states — a mild tilt toward prepayment.
Property tax growth. Remember that in Texas, the mortgage is often less than half the total housing cost once taxes and insurance are included. Paying off the mortgage early while ignoring a $9,000 annual tax bill is incomplete planning — budget the full carrying cost of the paid-off home. Shorter loan terms build equity faster and tilt the same trade-off — worth modeling before you choose your mortgage at origination.
When the Answer Is Clear-Cut
Prepay aggressively when: your rate is 7 percent or higher, you are near retirement and want the payment gone, you have maxed tax-advantaged accounts, or you lose sleep over debt. Invest instead when: your rate is under 4.5 percent, you have unused tax-advantaged space, your emergency fund is thin, or your time horizon exceeds 15 years. Split when: rates are 5 to 6.5 percent and none of the clear-cut conditions apply — which describes most Texas households right now.
Conclusion
Paying off the mortgage early versus investing is a comparison between a guaranteed return (your mortgage rate) and an expected one (market returns), filtered through liquidity needs, tax position, and peace of mind. At today’s rates, prepayment is a genuinely strong financial move — not just an emotional one — while investing still wins for low-rate mortgages and long horizons. Texas homeowners should add property taxes, homestead protections, and the absence of state tax benefits to the calculus. Run your own numbers with your actual rate, fund the hierarchy in order, and stop treating it as a loyalty test: the right answer is the one that fits your balance sheet, not someone else’s philosophy.
Frequently Asked Questions
Is it better to pay off my mortgage early or invest in Texas?
At mortgage rates of 7 percent or higher, prepaying offers an excellent guaranteed return. Below 4.5 percent, investing usually wins on expected returns. Between 5 and 6.5 percent, splitting the surplus is the balanced approach.
Does paying off my mortgage early save money in Texas?
Yes — substantially at higher rates. Extra payments on a 7 percent loan can save six figures in interest. But remember Texas property taxes and insurance continue after payoff, so total housing costs never go to zero.
Should I max my 401(k) before prepaying my mortgage?
Almost always yes — at minimum through the employer match, and usually through full tax-advantaged contributions if your mortgage rate is below 6 percent. Tax-advantaged space is use-it-or-lose-it each year.
What is the return on extra mortgage payments?
Exactly your mortgage interest rate, guaranteed and after-tax (for most households taking the standard deduction). A 7 percent mortgage means every prepaid dollar earns 7 percent risk-free.