
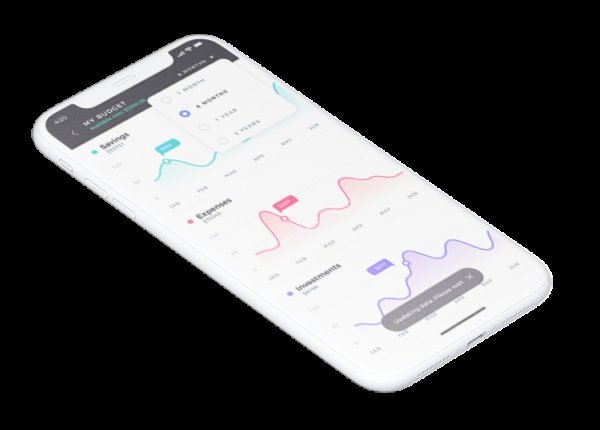
The alert that changes people is not complicated. It does not arrive as a lecture about savings rates. It lands mid-month, in plain words: dining out has eaten 80 percent of its budget, and there are nine days left. That one nudge — specific, early, and impossible to argue with — is the core of what AI budgeting tools actually do. They watch, continuously and without judgment fatigue, so the information reaches you while there is still time to act on it. Here is how that plays out across a real month, phase by phase.
Phase one, days 1–3: the setup nobody enjoys
Every budgeting tool begins with the same unglamorous work: connect your accounts, watch your spending get categorized, and correct the miscategorizations. There will be miscategorizations — the tool will file your pharmacy run as groceries and your work lunch as entertainment — and the first week’s corrections are what teach it your life. This setup cost is where most people quit, usually on day two, surrounded by financial plumbing.
It is worth pushing through, because everything later depends on it. A budget built on wrong categories produces confident, useless alerts. Aim for a simple category set you actually recognize — housing, groceries, eating out, transport, fun, the rest — rather than forty precise buckets you will never review. Set the monthly limits while your intentions are fresh, and set them at levels you could plausibly survive; a fantasy budget generates alerts you learn to ignore, which is worse than no alerts at all.
Phase two, week one: the first honest mirror
Within days, the tool assembles the first thing most people have never actually seen: their real spending pattern, complete and categorized, with no memory-based editing. This is the phase of surprises. The total spent on small, forgettable purchases — delivery fees, convenience runs, the subscription to something cancelled in your mind months ago — is usually the headline. AI tools are good at surfacing these because they are counting, not estimating, and counting is the one thing human budgeting never survives contact with.
The useful move in this phase is not shame; it is selection. Pick the one leak that is large, recurring, and low-value to you. Not the one that sounds virtuous to cut — your actual least-loved expense. One fix at a time is what the next phase is built on.
Phase three, mid-month: the nudge window
This is where AI budgeting earns its keep, and it is a timing advantage more than an intelligence advantage. A human review discovers the dining-out overrun on the 31st, in the autopsy. The tool’s pace-tracking spots the trajectory around the 12th: at the current rate, this category lands at 140 percent of budget. Alerts at this stage are still actionable — three fewer takeaways, one swapped plan, and the month recovers.
The tool’s monthly forecast extends the same logic forward: based on your recurring bills and current pace, it projects where the month ends before it ends. Watching a projected shortfall shrink as you adjust is, for many people, the first time budgeting has felt like steering instead of bookkeeping. Guard against the known failure mode, though: alert fatigue. If the app pings you daily, you will mute it by week three, and a muted budgeting tool is just an expensive list. Set alerts for category pace and unusual transactions, and silence the rest.
Phase four, month end: the fifteen-minute review
The month closes with a review that should take about fifteen minutes — a rhythm the original advice on this topic also lands on, and the number is about right. What did the categories actually do? Which limit was unrealistic rather than disobeyed? What is the one change for next month? AI tools compress this review by preparing it: the summary, the anomalies, the comparison with last month are assembled before you sit down, so your fifteen minutes go on decisions instead of arithmetic.
Be honest in this phase about circumstantial months. A month with a car repair or a wedding is not a failed budget; it is data about what your emergency fund is for. Tools that let you tag one-off expenses keep the regular pattern visible underneath, which is what you are actually managing.
Phase five, months two and three: where the “AI” part deepens
With a few months of your data, the predictions sharpen. The tool learns your genuine cycles — the expensive month, the cheap one, the annual bills that ambush people who think in months — and can start flagging subscription creep, duplicate services, and price rises on things you autopay and never see. This is also where pairing the tool with one deliberate habit pays off most: many people route the money the tool helped them find into savings automatically, the same week, before it dissolves back into spending. The broader money-housekeeping skills still matter — how to save money on groceries without using coupons will do more for most grocery budgets than any alert — and the CFPB’s consumer tools, including its budgeting worksheets, remain a solid free foundation under any app.
A note on budgeting with a partner
Shared finances add one complication the tool cannot solve and one it solves beautifully. The problem it cannot solve is agreement: two people with different ideas about what counts as a necessity will generate one budget and two realities, and software has no vote in that argument. Have the argument first, in words, about the three or four categories you genuinely disagree on.
What the tool does provide is a neutral scoreboard, and couples who use these apps often say that is the real gift. The numbers in the app are neither partner’s memory or version — they are simply the transactions. “Eating out is at 80 percent with nine days left” lands very differently from “you always overspend on eating out,” because the first is a fact about the month and the second is a claim about a person. Several tools allow shared views with personal categories kept separate, which supports the arrangement many households land on: shared limits for shared life, private allowances nobody has to justify. If money fights are your household’s recurring weather, that neutral third party in the phone is not a small thing.
When the month breaks anyway: the reset ritual
Some months, the alerts were right and life was louder. A vet bill, a broken boiler, a flight for a family emergency — the budget does not bend, it snaps, and what happens next decides whether the system survives. The failure mode to avoid is the abandoned app: a blown month quietly becomes a reason to stop looking, and by the time you return, three months of data have gone feral. The reset takes ten minutes. Acknowledge the month in the tool — tag the emergency for what it was, so the pattern underneath stays clean. Rebuild next month’s limits from the real numbers, not the aspirational ones, including a line for rebuilding whatever the emergency consumed. Then shrink the goal to something almost embarrassingly achievable for exactly one month: no category red at the end. Budgeting systems, like diets, are rarely killed by the binge; they are killed by the shame spiral after it. A tool that has shown you nine honest nudges has earned the tenth month — give it a month it can win.
What the tool will never do
Now the honest boundary. The tool cannot see cash spending, so a cash-heavy life reads as suspiciously frugal. It cannot know that this month’s restaurant spending was your sister’s once-a-year visit and worth every cent. It cannot want the goal for you — the debt paid off, the deposit saved — on the mornings when you do not. And it categorically cannot make the actual decision at the actual moment: the takeaway app open at 9 p.m. is a human problem with a human solution.
The verdict
Can AI help you actually stick to a monthly budget? Yes, in a specific and limited way: it removes the two excuses that kill most budgets — not knowing where the money went, and finding out too late. One practical footnote for anyone starting this week: give the tool a full month before judging it, including the setup corrections and at least one mid-month nudge cycle, because the first fortnight measures your plumbing more than your habits. The verdict the tool deserves is the one from the second month — the first month in which it was watching a system that had finished being built. What remains after those excuses are gone is the budgeting itself, which was always a set of choices rather than a set of calculations. People who succeed with these tools tend to describe the same arrangement: the app is the watchman, tireless and specific, and they are still the one who decides what the watchman is guarding. Set it up properly, keep the alerts few and meaningful, do the fifteen-minute review — and the nudge about dining out on day twelve will do the rest.

4 Comments