Christmas is not an emergency. It arrives on the same date every year, yet every December it lands on budgets like a surprise, paid for with credit cards and January regret. The same trick repeats all year long: the car repair that was always coming, the insurance deductible, the holiday travel, the vet bill. None of these are surprises. They are regular costs wearing irregular timing, and a sinking fund is the simple system that treats them that way. You save a small amount each month for a named future cost, so when the bill arrives, the money is already sitting there with its name on it.
Setting Up Your Sinking Funds in Six Steps
Step 1: List Your Irregular Expenses
Start by mining last year’s bank statements. Go month by month and pull out every bill that is not monthly but is absolutely coming: the costs that ambushed you, the annual renewals, the seasonal spending. Memory alone will miss half of them, because the whole problem is that these expenses fade from mind between appearances. Your statements remember what you forgot. Write every item down, even the small ones. The list is the foundation, and a fund cannot exist for a cost that never made the list.
Step 2: Estimate the Annual Cost of Each
Put a yearly number next to each item. Where you have evidence, use it. If car maintenance averaged $1,200 last year, then $1,200 is your figure, not a guess. If Christmas cost $800 last year, start there. Where you have no history, set a deliberate target instead: decide what you are willing for that cost to be this year, and fund the target. A holiday fund built on a chosen $600 limit does double duty, because it sets the spending ceiling at the same time as it saves toward it. Round numbers are fine. Precision matters far less than having a number at all.
Step 3: Divide by Twelve
Now turn each yearly figure into a monthly one by dividing by twelve. The $1,200 a year of car maintenance becomes $100 a month. The $600 of holiday spending becomes $50 a month. That is the entire trick, and it is arithmetic a child can check. A frightening $1,200 bill becomes a calm $100 line in the monthly budget. Add up the monthly amounts for all your funds and you have one total figure: the amount that moves into your sinking funds each month so the future stops ambushing you.
Step 4: Create the Containers
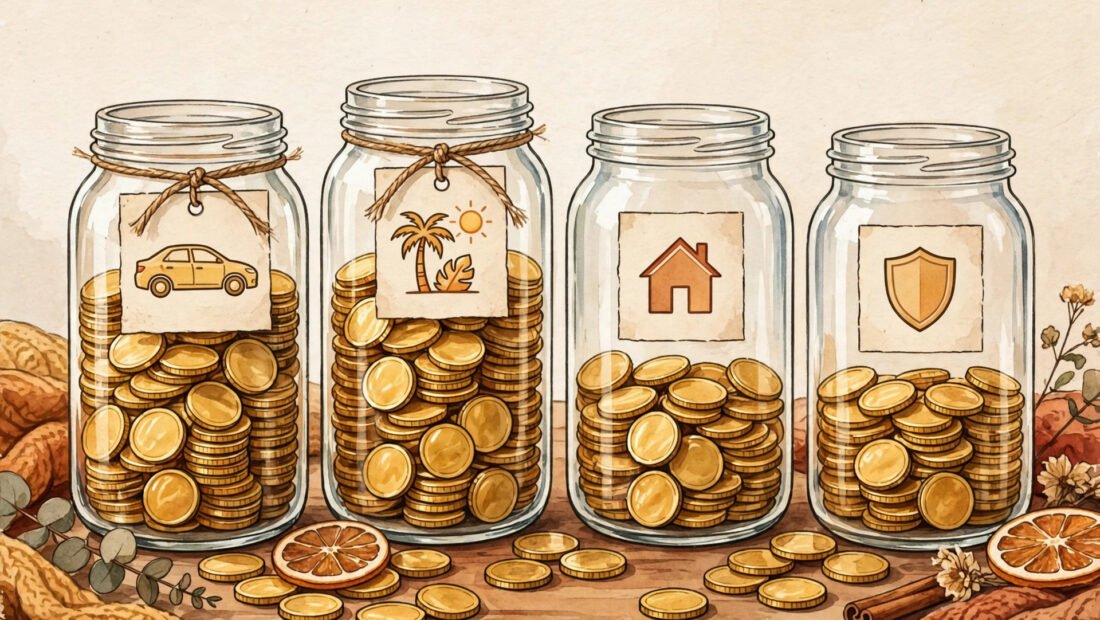
Give the money somewhere separate to live. Use labelled savings buckets or sub-accounts, one per fund, which many banks and savings apps now offer inside a single account. The car fund holds car money. The holiday fund holds holiday money. Labels sound like a small thing, but they do the heavy lifting in this system, because money with a name behaves differently from money in a general pile. An unnamed $800 balance looks spendable. An $800 balance labelled for the car and the deductible looks spoken for, because it is. If your bank offers no buckets, separate savings accounts for your two or three largest funds still work well.
Step 5: Automate the Transfers
Set the transfers to run on their own, timed to land the day after payday. This step is not optional decoration. A system that depends on monthly willpower is not a system, because willpower has bad months exactly when money is tight. Automation moves the money before you can negotiate with yourself about it, while your pay is fresh and before the month’s spending begins. Treat the transfer like any other bill: fixed, scheduled, and not up for monthly debate. Households that prefer a low-friction approach to the whole budget often pair this with budgeting without spreadsheets, keeping the automation and dropping the paperwork.
Step 6: Spend From the Fund, Guilt-Free
When the bill lands, pay it from its fund and feel nothing but calm about it. Here is the worked moment this whole system exists for: a $900 car repair arrives, and the car fund holds $1,100. You pay the $900 without stress, without credit cards, and without raiding money meant for anything else. No juggling, no collateral damage to the rest of the month. That quiet transaction is not a side benefit of sinking funds. It is the point of them. Money saved for a purpose and then used for exactly that purpose is the system working, not the system being spent.
The Twelve Funds Most People Forget
Most people remember holidays and car repairs and stop there. These twelve are the ones that slip past, counted so you can check your own list against them.
One, car repairs. Tires, brakes, batteries, and the failures no one schedules. Two, home maintenance. Use the 1-percent rule: budget 1 percent of your home’s value per year, which is $250 a month on a $300,000 Texas home. Roofs and air conditioners do not care that the timing is bad. Three, the health insurance deductible. A $3,000 deductible is a $250-a-month fund if you want a bad health year to stay a health event and not become a debt year. Four, holidays. Gifts, food, travel, and the extras December piles on. Five, travel. Trips planned a year out still need paying for. Six, weddings and their travel. A single event with flights, a hotel, and a gift easily runs $500-plus. Seven, vet bills. Routine care is predictable, and older pets add the rest. Eight, technology replacement. Phones and laptops die on a rough schedule whether you fund it or not. Nine, the next car. Saving toward a replacement turns a future loan into a future choice. Ten, gifts beyond holidays. Birthdays, graduations, and new babies arrive all year. Eleven, annual subscriptions and renewals. Small charges, dozens of them, all renewing at once if you let them. Twelve, school-season costs. Supplies, clothes, fees, and activity costs land every year at the same time, just like Christmas.
You do not need all twelve on day one. Pick the ones that have actually ambushed you, check them against this list for gaps, and let the rest wait until your first funds are running smoothly.
What a Realistic Starting Month Looks Like
The totals can sound large until you watch them build from the examples already used here. The car fund asks for $100 a month. The holiday fund asks for $50 a month. Those two alone cover the two costs that ambush most households hardest, for $150 a month moved the day after payday. Add the health deductible fund at $250 a month only if your budget can carry it now; if it cannot, start it lower and raise it later, because a partly filled deductible fund still turns a crisis into a smaller crisis. The system grows by addition over time, not by one heroic first month, and each fund you add removes one more named ambush from your year.
Where to Keep the Money
Keep sinking funds in a high-yield savings account. It is close enough to reach in a day when the repair shop calls, and separate enough that you do not spend it by accident during an ordinary week. The interest is a pleasant extra rather than the goal. What matters is the separation: out of your main spending account, clearly labelled, and boring. Money earmarked for a roof or a deductible has no business riding the ups and downs of investments, and it has no business sitting where a routine shopping trip can quietly absorb it. For broader official guidance on accounts and saving, the CFPB’s consumer guidance on budgeting and saving is a solid reference point.
Not an Emergency Fund
One distinction keeps the whole system clean, so it is worth stating once and clearly. The emergency fund is for surprises: a job loss, a genuine crisis, the expense nobody could have seen coming. Sinking funds are for certainties wearing a disguise: costs you know are coming, where only the timing is fuzzy. Christmas does not belong in the emergency fund. Neither does the car repair on a car with high miles. When predictable costs drain the emergency fund, the real emergency, when it comes, finds the cupboard bare. Keep the two pots separate and let each do its own job.
Common Mistakes
Three mistakes undo more sinking funds than any shortage of money. The first is starting twelve funds at full strength at once. The total monthly figure looks heroic on paper and collapses by February. Start by funding your top three properly — usually car repairs, home maintenance, and holidays — and add the rest one at a time as the habit settles. Three funded funds beat twelve starved ones.
The second mistake is raiding a fund for a want and calling it borrowing. A sale, a gadget, a weekend away that was never a travel-fund plan: the moment a fund becomes a general pot for impulses, every fund becomes one, and the next real bill goes back on a credit card. If money must move between funds for a genuine reason, move it on paper, name it, and adjust the monthly amounts to repair the gap.
The third mistake is keeping the money in the current account where it evaporates. In a spending account, fund money blends into the balance, gets counted as available, and leaks away in small amounts nobody remembers. That is why the separate account in step four matters as much as the arithmetic in step three. The system is six small steps, a separate labelled home for the money, and transfers you never have to remember. Set it up once, and December goes back to being a holiday instead of an ambush.